Understanding Pension Pillars and Retirement Savings in Croatia
Navigating the labyrinthine world of pension systems can feel like a daunting task in any country, let alone when you're an expat trying to make sense of a new system in Croatia. It’s easy to feel overwhelmed by the unfamiliar terms, the different pillars, and the worry about whether your contributions now will actually translate into a comfortable retirement later. This guide is here to cut through the confusion, offering a clear, empathetic breakdown of Croatia’s pension pillars and how they apply to your retirement savings journey as a foreigner living here.
The Foundations of the Croatian Pension System: A Multi-Pillar Approach
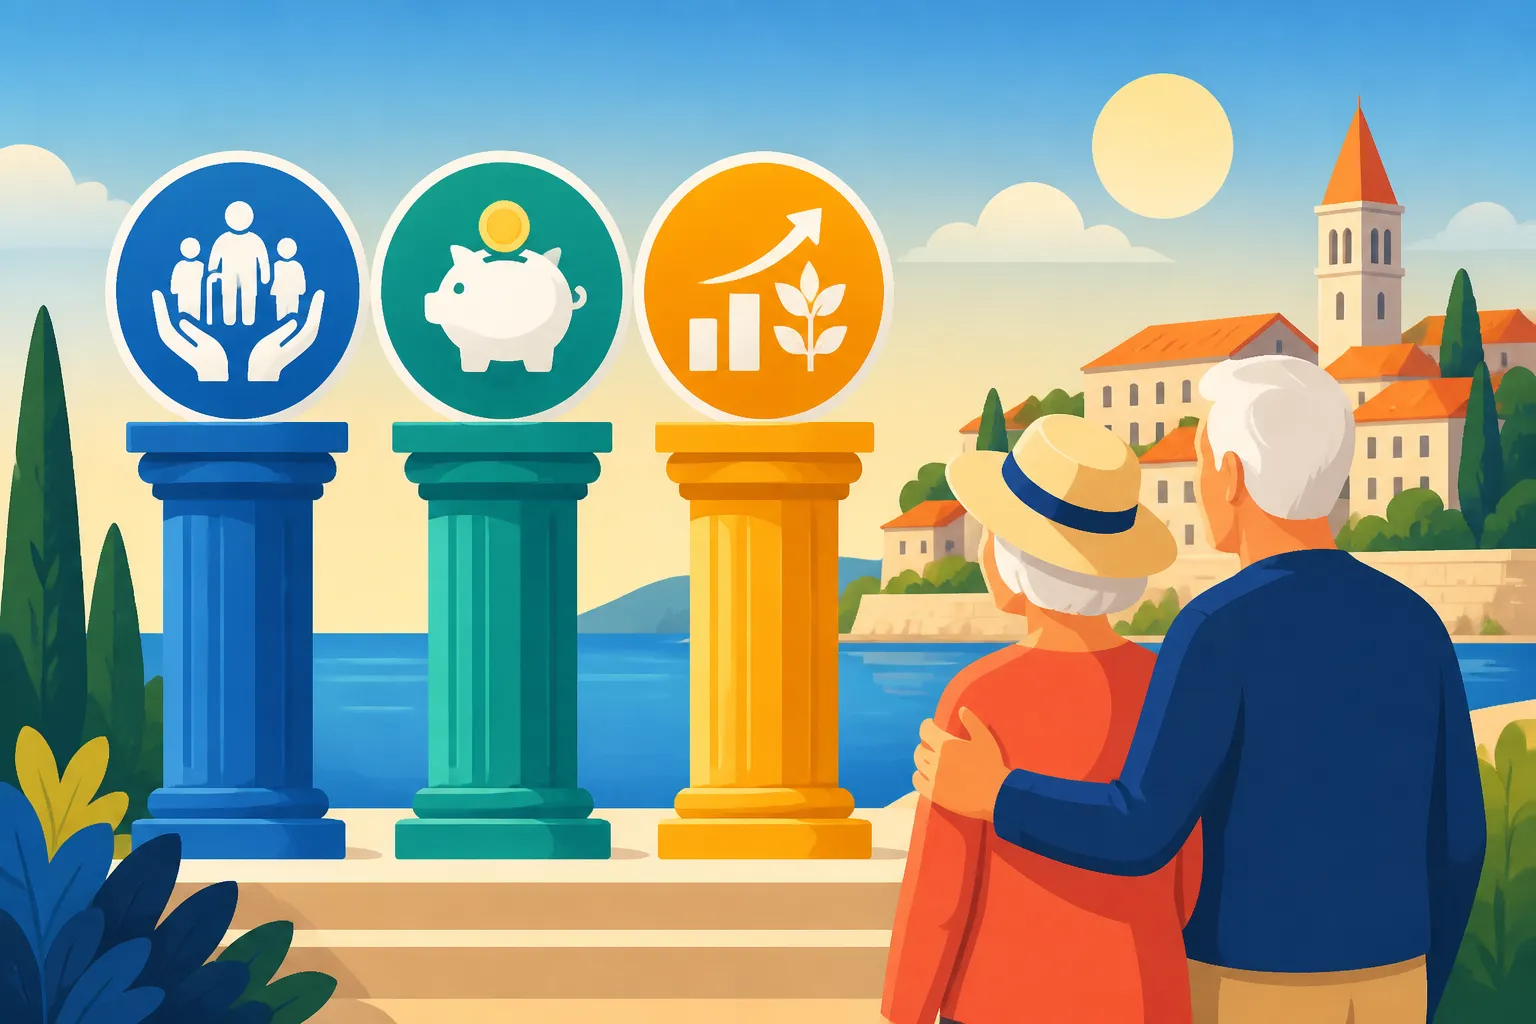
Croatia operates a multi-pillar pension system, designed to provide a comprehensive framework for retirement security. It’s a bit different from what you might be used to, combining elements of a traditional pay-as-you-go system with individual savings accounts. Understanding these foundational pillars is crucial for anyone planning their long-term financial future in this beautiful country. It's not just about ticking a box; it's about ensuring your hard-earned money is working for you in the long run.
The First Pillar: Mandatory State Pension Generational Solidarity
This is the bedrock of Croatia's pension system, often referred to as the "generational solidarity" pillar. Think of it as a social contract: the working generation contributes to pay the pensions of the current retirees. It’s a classic pay-as-you-go (PAYG) system, managed by the Croatian Pension Insurance Institute (Hrvatski zavod za mirovinsko osiguranje, or HZMO).
Every employed person in Croatia, whether local or expat, contributes to this pillar. The contributions are a mandatory percentage of your gross salary, automatically deducted by your employer. If you're self-employed, like many digital nomads or entrepreneurs running a paušalni obrt, you’ll be responsible for paying these contributions yourself, usually on a monthly basis. These funds don't accumulate in a personal account for you; instead, they go into a general pool to support current pensioners. While it might feel abstract, this pillar provides the basic safety net for everyone. The idea is that when you retire, the then-working generation will be contributing to your pension. It’s a system built on collective responsibility, aiming to ensure a minimum level of income security for all retirees. This aspect is crucial for understanding your social security contributions, which is covered in more detail in our guide on Understanding Social Security Contributions (Doprinosi) in Croatia.
The Second Pillar: Mandatory Individual Capitalised Savings Defined Contribution
Introduced in 2002, the second pillar represents a significant shift towards individual responsibility in retirement planning. Unlike the first pillar, this one is a defined contribution system, meaning your contributions are paid into a personal pension account, managed by a chosen pension fund. These funds invest your contributions, and the value of your pension at retirement depends on how much you’ve contributed and how well your chosen fund's investments have performed over the years.
When you start working in Croatia and your contributions begin, you’ll typically be automatically assigned to one of the mandatory pension funds (Mirovinski fondovi). However, you have the right to choose your fund and even switch between them if you’re not happy with the performance or management fees. These funds are regulated and aim for long-term growth, but like any investment, they carry some level of risk. This pillar is designed to supplement the first pillar, providing an additional layer of financial security that is directly tied to your individual savings and the market performance. It’s a way to personalize your pension somewhat, giving you a stake in its growth. The funds are categorized by risk profile, typically A, B, and C, with A being the riskiest (and potentially highest return) and C being the most conservative. Most younger workers are initially placed in a riskier fund (Category B) to benefit from long-term growth, while those closer to retirement are shifted to more conservative options.
Navigating the Mandatory Contributions for Expats
As an expat, understanding your mandatory contributions is paramount. It’s not just a formality; it’s a critical component of your legal status and future financial security in Croatia. Many expats find this part particularly challenging due to language barriers and the often-unspoken administrative rules.
Who Must Contribute and How
Virtually everyone legally working in Croatia is required to contribute to the pension system. This includes both EU and non-EU citizens, provided you are employed by a Croatian company or are officially self-employed within the country.
- For Employees: If you're an employee, your life is relatively simple on this front. Your employer is legally obliged to deduct your pension contributions directly from your gross salary and pay them on your behalf to the relevant state institutions (HZMO and Regos). This means your payslip will show deductions for both the first and second pillars. You'll often see these listed under "mirovinsko osiguranje" or similar terms. It’s part of the broader system of taxes and social contributions, which are important to understand for anyone working in Croatia. For a comprehensive look at how income is taxed, you might want to review our guide on Understanding Income Tax Rates and Brackets in Croatia.
- For Self-Employed Individuals: If you're a freelancer, a contractor, or running an obrt (crafts business) or a popular paušalni obrt, you bear the responsibility of paying your own contributions. This can be a bit more hands-on. Your contributions are typically calculated based on a specific contribution base set by the state, not directly on your actual income, especially for paušalni obrt owners who pay a flat rate regardless of profit. These payments are usually made monthly, directly to the Croatian Tax Administration (Porezna Uprava). It's crucial to stay on top of these payments, as any delays can incur penalties. Getting your OIB (personal identification number) sorted is one of the very first steps in this process, as it's the identifier for all your financial dealings, including pension contributions. Our guide, How to Get Your OIB and Why It Matters for Healthcare Access, can give you more insights here. While digital nomads might seem like an exception, if you opt for the digital nomad permit and are working for a foreign company, you typically aren't required to contribute to the Croatian pension system. However, this also means you won’t accrue Croatian pension rights, so planning for private retirement savings becomes even more critical.
| Category | First Pillar (HZMO) | Second Pillar (Mandatory Pension Fund) | Payment Method | Responsibility |
|---|---|---|---|---|
| Employee | Mandatory | Mandatory | Deducted from gross pay | Employer |
| Self-Employed | Mandatory | Mandatory | Monthly direct payment | Individual |
| Digital Nomad | Not Mandatory | Not Mandatory | N/A | N/A (unless opting in) |
Understanding Your Pension Statement and Tracking Contributions
This is where the rubber meets the road, and sometimes, where the frustration sets in. You absolutely need to keep track of your contributions. The Croatian Pension Insurance Institute (HZMO) and the Central Registry of Insured Persons (Regos) are your primary sources of information. Regos is particularly important as it records all your contributions to both the first and second pillars.
You can usually access your pension statement (often called a "Mirovinska kartica" or "izvješće o stažu i plaći") through the e-Građani portal, Croatia's e-government platform. This platform requires you to have a certain level of digital identification, which itself can be a multi-step process for expats. Once you're in, you can typically generate a report that shows your years of service, periods of insurance, and the bases on which your contributions were paid. For the second pillar, your chosen pension fund will also send you annual statements detailing the performance of your investments and the accumulated value in your individual account. It's crucial to review these statements carefully. Mistakes can happen, and if your contributions aren't recorded correctly, it can impact your future pension. Don’t be shy about contacting HZMO or your pension fund if something looks amiss. It might feel like a bureaucratic headache, but ensuring accuracy now can save you a world of pain down the line. Keep all payslips, contracts, and any other documentation that proves your employment and contributions. This diligence is especially vital for expats who might eventually move to another country, as consolidating records can become a complex task.
The Third Pillar: Voluntary Retirement Savings and Supplementary Options
While the first two pillars are mandatory, the third pillar offers a flexible, voluntary avenue for boosting your retirement savings. For many expats, this pillar, along with private investment strategies, will be key to achieving a truly comfortable retirement in Croatia. It’s about taking control beyond the state-mandated minimum.
Voluntary Pension Funds Individual and Professional
The third pillar consists of voluntary pension funds (dobrovoljni mirovinski fondovi). These funds are entirely optional and are designed to provide supplementary income in retirement. They operate on a defined contribution basis, similar to the second pillar, meaning your payout depends on your contributions and investment returns.
There are two main types:
- Open Voluntary Pension Funds: These are accessible to anyone, regardless of their employment status. You can contribute to them individually, setting up regular payments or making one-off deposits. Many individuals choose this route to top up their retirement savings.
- Closed Voluntary Pension Funds: These are typically established by employers for their employees, often as a benefit. While still voluntary for the employee, the employer also contributes, making them an attractive option if your company offers one.
One of the significant advantages of the third pillar funds is the tax incentives offered by the Croatian government. Your contributions, up to a certain annual limit (currently €660 or 5,500 HRK), are tax-deductible from your taxable income. This means you effectively get a discount on your savings, making it an appealing option for those looking to optimize their tax situation while planning for the future. The accumulated funds are also generally tax-exempt until withdrawal. This can be a smart move for expats who are tax residents in Croatia and want to maximize their long-term savings. When you're thinking about your overall financial picture in Croatia, you'll find that managing these different types of contributions and potential tax breaks becomes part of a larger strategy, which ties into the broader subject of The Complete Guide to Taxes in Croatia for Expats.
Other Personal Savings and Investment Strategies
Relying solely on the state pension and even the mandatory second pillar might not be enough for the retirement lifestyle many expats envision. This is where personal savings and broader investment strategies come into play. Diversifying your investments beyond formal pension funds is a wise move, particularly if you have a significant portion of your working life outside Croatia or if you're a digital nomad not contributing to the Croatian system.
Many expats choose to invest in real estate in Croatia, not just for personal use but also as a long-term asset that can generate rental income or appreciate in value. Others opt for a more global approach, investing in stocks, bonds, or mutual funds through international brokerage platforms. The key here is to consider your risk tolerance, time horizon, and financial goals. For those with complex financial situations, particularly those with assets or income streams in multiple countries, seeking advice from specialists can be invaluable. Firms like Taxes for Expats, for instance, specialize in helping individuals navigate international tax complexities, which often includes advice on how foreign investments and pension income might be treated under various tax treaties. This kind of specialized guidance can prevent nasty surprises down the road. Remember, while Croatia offers certain tax advantages for long-term residents, international investments come with their own set of rules and implications, making professional advice a sound investment in itself.
Retirement Age, Conditions, and Calculating Your Pension
Understanding when you can retire and how your pension will be calculated is naturally one of the most pressing concerns for anyone, especially expats trying to plan their lives in a new country. Croatia's system, like many, has specific requirements and formulas that can seem opaque at first glance.
Standard Retirement Age and Early Retirement Options
Croatia has been gradually increasing its retirement age for both men and women to align with other EU member states.
-
Standard Retirement Age (Starosna mirovina):
- For Men: The current retirement age for men is 65 years.
- For Women: The retirement age for women is incrementally increasing. As of 2024, it is 63 years and 9 months, and it will continue to rise until it reaches 65 years in 2030, at which point it will be equalized with men's retirement age.
- In addition to age, you typically need a minimum of 15 years of pensionable service (staž osiguranja) to qualify for a basic state pension.
-
Early Retirement (Prijevremena starosna mirovina): It is possible to retire earlier than the standard age, but there are specific conditions and usually penalties.
- For Men: You can opt for early retirement from age 60, provided you have at least 35 years of pensionable service.
- For Women: As of 2024, early retirement for women is possible from 58 years and 9 months, with at least 33 years and 9 months of service. This age and service requirement will also gradually increase until it reaches 60 years and 35 years of service, respectively, by 2030.
- However, choosing early retirement comes with a reduction in your pension amount for each month of early retirement. This reduction is permanent, so it’s a decision that requires careful consideration and financial planning. The reduction rates are quite significant, designed to discourage early withdrawal from the system. It's often recommended to seek advice from HZMO or a financial advisor to fully grasp the long-term impact of early retirement on your pension income.
How Your Pension is Calculated in Croatia
Calculating your future pension in Croatia is notoriously complex, as it factors in various elements from both the first and second pillars. It's not a simple sum of your contributions.
- For the First Pillar (HZMO): The calculation for the state pension largely depends on your total years of pensionable service (staž), your average gross earnings throughout your career (which are then "valorized" or adjusted for inflation and economic growth), and a valorization factor applied by HZMO. The formula is designed to reflect both the length of your contributions and the level of your earnings. This means that generally, the longer you’ve worked and the higher your earnings, the larger your first-pillar pension will be. However, there are caps on the highest earnings considered, and floors for the lowest, ensuring a degree of social equity.
- For the Second Pillar (Mandatory Pension Funds): Your second-pillar pension is determined by the accumulated capital in your individual account. This capital is the sum of all your contributions plus the investment returns generated by your chosen pension fund, minus any fees. When you retire, this accumulated capital is converted into an annuity, which provides a regular income stream. You’ll typically have options on how this annuity is paid out – for a fixed period, for life, or with survivor benefits.
- The "Two-Pillar" Pension Payout: If you’ve contributed to both pillars, your total pension income will be a combination of the first-pillar state pension and the second-pillar annuity. HZMO will calculate your potential first-pillar pension, and then factor in the second pillar. There are rules that dictate how these two are combined to ensure a fair overall pension, sometimes even offering a choice between receiving the entire pension from HZMO (if more favorable for those with lower second-pillar accumulations) or the split approach. Estimating this can be particularly challenging for expats who have fragmented work histories across different countries, as the Croatian system needs to integrate those periods, if applicable, through international agreements.
International Considerations and Cross-Border Pensions
For expats, the question of how their Croatian pension contributions integrate with their work history in other countries is often the most complex and critical. Will your years of service in Croatia count if you retire elsewhere? What about your contributions from your home country if you retire in Croatia? The answers depend heavily on international agreements.
EU/EEA/Switzerland Social Security Coordination
One of the great advantages of being an EU/EEA or Swiss citizen, or having worked in these regions, is the principle of social security coordination. This means that your periods of insurance (contributions) in one member state are generally recognized by other member states when it comes to calculating your pension.
- Aggregation of Periods: If you’ve worked in multiple EU/EEA/Switzerland countries, each country where you contributed will calculate a portion of your pension based on the periods you worked there. When you apply for your pension, usually in the country where you last worked, the authorities will aggregate all your periods of insurance from different member states. This doesn't mean your contributions are transferred, but rather that each country acknowledges the time you spent contributing elsewhere.
- Pro-Rata Pension: Each country will then pay you a pro-rata pension, meaning a portion of your overall pension calculated based on the length of your contributions to their specific system. So, if you worked 10 years in Germany and 20 years in Croatia, Germany would pay you a portion of your pension based on those 10 years, and Croatia would pay a portion based on 20 years.
- Applying for Your Pension: You typically apply for your pension in the country where you last worked, or in your country of residence, if different. That country's pension authority will then liaise with the pension institutions in all the other countries where you contributed to gather the necessary information and process your claim. This system is designed to prevent you from losing out on pension rights just because you moved between member states. This portability is a huge relief for many, allowing them to truly build a pan-European career without sacrificing their retirement security.
Bilateral Social Security Agreements and Non-EU Citizens
For non-EU citizens, or those from countries outside the EEA and Switzerland, the situation is a bit more nuanced.
- Bilateral Agreements: Croatia has entered into bilateral social security agreements with a number of countries around the world. These agreements are crucial because they ensure that periods of insurance completed in one signatory country are recognized in the other, often preventing double contributions or the loss of pension rights. For example, Croatia has agreements with countries like Canada, Australia, and the US (though the US agreement is specific to totalization for social security benefits). The specific terms of these agreements vary greatly, so it’s essential to check if your home country has one with Croatia and what its provisions entail. These agreements dictate how contributions are handled, how periods of service are aggregated, and how claims are processed.
- No Agreement Exists: If your home country does not have a bilateral social security agreement with Croatia, the situation becomes considerably more complex. In such cases, your contributions to the Croatian pension system might only be recognized by Croatia, and your contributions in your home country might only be recognized there. This means you could end up with a smaller pension from each country, as neither acknowledges the full scope of your working life. You might face challenges in aggregating periods of service, potentially leading to situations where you meet the minimum service requirement in neither country. This is where professional advice becomes not just helpful, but often essential. Experts like Taxes for Expats frequently assist individuals in understanding the implications of these gaps and how to best structure their finances to mitigate potential losses. It's a key area where careful planning and expert consultation can make a significant difference to your future retirement income.
Practical Advice and Resources for Expats Planning Retirement in Croatia
Retirement planning in a foreign country requires proactive steps and diligent management. As an expat in Croatia, you have unique challenges, but also unique opportunities to secure your financial future here.
Essential Steps for Managing Your Pension as an Expat
Taking charge of your pension situation from day one will save you immense stress later. Don’t leave this to chance or assume things will sort themselves out.
- Get Your OIB Sorted Immediately: Your OIB, or personal identification number, is your key to absolutely everything in Croatia, including your pension. Without it, your contributions cannot be properly recorded. Make it one of your first priorities upon arrival. For more details, refer to our guide, How to Get an OIB (Personal Identification Number) in Croatia.
- Keep Meticulous Records: This cannot be stressed enough. Retain every single payslip, employment contract, self-employment registration document, and any correspondence from HZMO or your pension fund. If you move countries, this paper trail will be invaluable for proving your contributions and service periods.
- Regularly Check Your Pension Statements: Don’t wait until you’re nearing retirement. Make it a habit to periodically access your statements from Regos (via e-Građani) and your second-pillar pension fund. Verify that your periods of service and contribution amounts are accurate. If you spot any discrepancies, address them immediately with HZMO or your employer.
- Understand Your Tax Residency: Your tax residency status impacts not only your current income tax but also how your pension income might be taxed in the future, particularly if you're receiving pensions from multiple countries. Ensure you understand the rules for Tax Residency in Croatia: A Definitive Guide for Expats (2027).
- Consider Professional Financial Advice: Especially if you have a complex international background, involving multiple countries, different currencies, or various investment vehicles, a financial advisor specializing in expat finances can be a game-changer. They can help you understand the intricacies of Croatian and international pension laws, optimize your voluntary contributions, and structure your investments to meet your retirement goals.
Financial Planning Tools and Transferring Funds
Modern financial tools can greatly simplify managing your money across borders, which is particularly relevant when dealing with pension payouts or consolidating retirement savings.
Many expats find online money transfer services incredibly useful. When it comes to receiving pension payments from abroad or transferring your savings into Croatia for investments, using platforms like Wise can offer significant advantages. They often provide more favorable exchange rates and lower fees compared to traditional banks, making sure more of your money actually reaches your account. For instance, if you're consolidating funds from an old pension scheme in your home country or receiving a regular pension payment from another EU state, a service like Wise can minimize the cost of currency conversion and international transfers. This ties into the broader topic of managing your finances internationally, which is further explored in our guide, How to Transfer Money Internationally from a Croatian Account.
Beyond transfers, consider budgeting tools or financial planning software that can integrate accounts from different countries. This holistic view of your finances is essential for effective retirement planning. Think long-term: where will you reside in retirement, what will your income streams be, and what are the tax implications of those streams? The beauty of living in Croatia is the incredible lifestyle, but ensuring financial peace of mind for your later years is just as important. Don't be afraid to ask questions, seek expert help, and leverage the tools available to build a robust retirement plan.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, legal, or tax advice. While we strive to provide accurate and up-to-date information, pension laws and regulations in Croatia are subject to change. It is highly recommended that you consult with a qualified financial advisor, tax professional, or the Croatian Pension Insurance Institute (HZMO) for advice tailored to your specific situation.